Manufactured Housing Market 2026: The Data, Constraints and Growth Opportunity
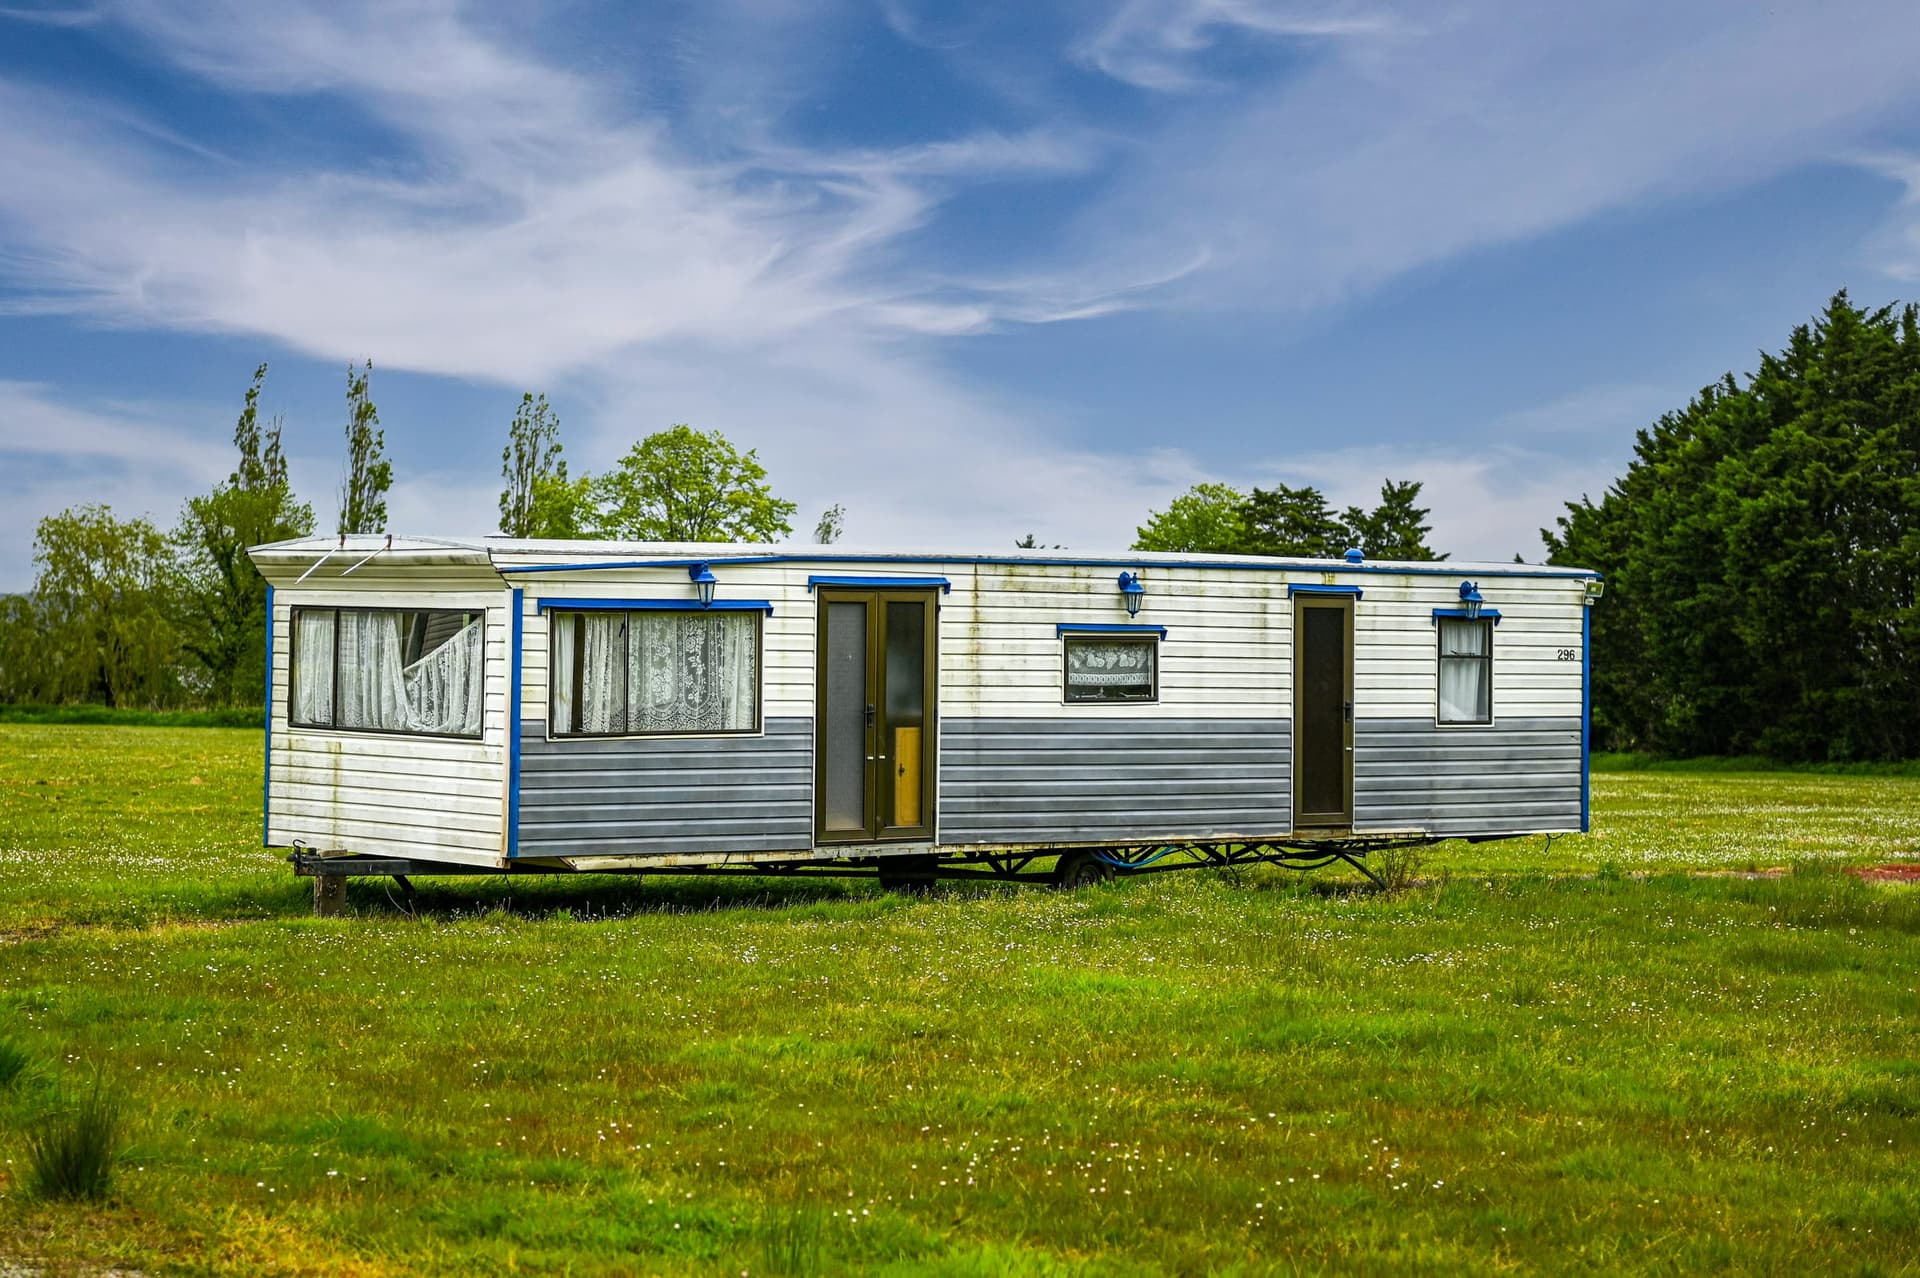
Manufactured housing is not waiting to become relevant to America's affordability crisis. It is already serving more than 20 million residents, shipping more than 100,000 new homes per year, and producing new homes at a structural cost that conventional construction struggles to match.
The category's largest barrier is not the ability to build a house in a factory. It is the fragmented system around the house: land, zoning, installation, title, financing, appraisal, community policy, listing data, and consumer discovery.
The 2026 opportunity is to improve that system.
2025 Closed With More Than 100,000 Shipments
The Census Bureau reports 102,700 new manufactured-home shipments in 2025, compared with 103,300 in 2024 and 89,200 in 2023.
Through May 2026, preliminary shipments totaled approximately 41,400, compared with about 45,000 in the first five months of 2025. The pace is softer, but one partial-year comparison should not be confused with a structural verdict on the category.
Demand depends on interest rates, dealer inventory, land availability, consumer confidence, site development, and regional housing conditions.
Prices Rose, but the Cost Advantage Remains
The average sales price of a new manufactured home reached $127,200 in 2025, up from $123,300 in 2024.
By configuration:
- Single-section average: $85,600
- Double-section average: $157,100
- All-home average size: 1,471 square feet
The 2024 Census comparison calculated an average manufactured-home structure cost of about $84 per square foot, compared with about $169 per square foot for the derived site-built structure component. The figures exclude land and should not be treated as an installed-project comparison, but they show the production advantage clearly.
Manufactured housing's strategic value is not that it is immune to inflation. It is that the factory model can deliver substantially more efficient structural economics.
Placement Data Shows the Market Is Broader Than Communities
In 2025, an estimated 70,700 new manufactured homes were sold and placed for residential use in the Census annual characteristics data.
Of those:
- Approximately 26,600 were inside communities or planned developments
- Approximately 18,700 were specifically in land-lease manufactured-home communities
- Approximately 44,100 were outside communities
The data challenges the stereotype that manufactured housing is synonymous with land-lease parks. Private-property placement is a major part of the current market.
Personal-Property Titling Remains Dominant
The same 2025 characteristics data estimates that 50,900 placed homes were titled as personal property, compared with 15,600 as real estate and 4,200 not titled.
That means the financing and consumer-protection conversation cannot focus only on real-property mortgages. Chattel and personal-property lending remain central to the category.
CFPB research has found that chattel borrowers generally pay higher interest rates, face higher denial rates, and refinance less often than manufactured-home mortgage borrowers. Improving responsible financing access is not a side issue. It is a market-expansion strategy.
The HUD Code Is Evolving
HUD finalized its most extensive update to the Manufactured Home Construction and Safety Standards in more than three decades in 2024. The update included 90 new or revised standards and enabled multi-unit single-family manufactured homes under the HUD Code, with fire-safety and other requirements.
In June 2026, HUD proposed revising the manufactured-home definition to support multi-story designs by allowing upper-floor sections to be transported and constructed without a permanent chassis. As of August 2026, that is a proposal, not a final rule.
The direction is important. Manufactured housing is expanding from a detached-home affordability product toward a broader off-site construction platform that could serve infill, denser development, and new design types.
Energy Rules Remain in Motion
The Department of Energy has issued manufactured-housing energy-conservation standards but postponed compliance deadlines while related enforcement procedures and policy issues are considered.
For consumers, the practical lesson is to compare the actual home's insulation, windows, HVAC, air sealing, climate design, and utility expectations rather than relying on a generic new-versus-old assumption.
For manufacturers and retailers, energy performance is both a compliance issue and a lifetime-affordability value proposition.
Four Constraints Will Determine Growth
1. Land and Local Approval
Factory capacity cannot solve zoning bans, restrictive minimums, slow permitting, utility constraints, or a lack of approved sites.
2. Financing
The market needs competitive mortgage and personal-property financing, clear consumer protections, and lender participation across more home and land structures.
3. Accurate Data and Appraisal
Thin comparable sets and poor classification make valuation harder. Better MLS participation and richer manufactured-housing fields improve transparency.
4. Consumer Discovery
Manufactured-home inventory is often fragmented across dealers, communities, local agents, personal-property marketplaces, and traditional MLSs. Buyers need a reliable way to search the category nationally without losing the land, lease, community, and home-specific details.
The Role of MHAuthority and MyStateMLS
Market infrastructure does not need to be theoretical. MyStateMLS already provides nationwide MLS services for manufactured housing, including homes on leased land. MHAuthority gives consumers a specialized place to search manufactured and mobile homes for sale or rent and explore communities.
That connection addresses a structural problem: accurate professional listing input paired with manufactured-housing-specific consumer discovery.
The more complete and visible the data becomes, the easier it is for buyers to compare, lenders to evaluate, appraisers to support, sellers to price, and professionals to participate.
A 2026 Strategic Agenda
The industry should prioritize:
- More approved sites and zoning pathways
- Broader responsible financing
- Consistent title and conversion processes
- Better installation and documentation
- Richer MLS data fields
- Category-specific consumer search
- Professional education for agents and appraisers
- Energy and lifetime-cost transparency
- Community stability and resident protections
- Modern messaging that is accurate rather than defensive
Frequently Asked Questions
Are manufactured-home shipments growing?
Shipments rose from about 89,200 in 2023 to 103,300 in 2024, then held near that level at 102,700 in 2025. Preliminary 2026 data through May trails the same period in 2025.
What is the average price of a new manufactured home?
The 2025 national average was $127,200, excluding land. Site work, delivery, installation, utilities, permits, improvements, and financing can increase the completed cost.
Are multi-unit manufactured homes legal?
HUD's 2024 standards update enabled manufactured homes with up to four dwelling units under specified requirements. Local land-use, building, installation, utility, and other approvals still apply.
The Bottom Line
Manufactured housing has already proven its production economics. The next phase depends on infrastructure around the home.
Land, financing, title, appraisal, listing data, and consumer search will determine whether the category remains artificially fragmented or becomes a fully integrated part of the national housing market.
MHAuthority and MyStateMLS are positioned at that integration point: professional data in, specialized consumer discovery out.